
Snapshot:
• After a storm hits Pompano Beach, acting quickly on roof damage protects your home and your insurance claim.
• Florida law sets a one-year deadline to file initial roof damage claims, making prompt professional inspection critical.
• Pro Contractors USA offers roofing services including shingle and tile options for South Florida homeowners.
When storm damage strikes a Pompano Beach roof, the decisions you make in the first 48 to 72 hours directly affect both your home’s safety and your ability to recover insurance costs. Knowing what steps to take, and who to call, makes the difference between a smooth repair and a denied claim.
If you are searching for a Roofing Contractor In Pompano Beach FL, the most important qualification to verify is that the contractor understands Florida’s coastal building codes, the state’s specific insurance claim rules, and the roof systems most common in Broward County. Not every general contractor meets that standard.
What Storm Damage Looks Like on a South Florida Roof
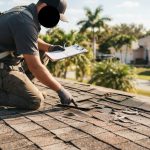
Pompano Beach sits squarely in South Florida’s hurricane corridor, and roofs here absorb punishment from wind, rain, and salt air year-round. After any named storm or severe weather event, inspect for these warning signs before calling your insurer:
• Missing, cracked, or lifted shingles
• Granule loss visible in gutters or on the ground
• Cracked or displaced clay and concrete tile sections
• Soft spots or bubbling on flat roof membranes
• Water stains on interior ceilings, which often indicate a breach that formed during the storm
Florida homeowner and commercial policies typically cover roof damage when it results from a sudden, accidental event, such as hurricane-force winds tearing shingles or wind-driven rain entering through storm-created openings. However, they typically exclude pre-existing deterioration, installation defects, and long-term leaks. A licensed roofing contractor documents the distinction between storm-caused damage and pre-existing wear, which is exactly what an adjuster will scrutinize.
Florida’s Claim Deadlines and the 25% Rule
Filing a roof insurance claim in Florida means navigating a one-year notification deadline, a 25% rule that can require full roof replacement, hurricane deductibles of 2% to 5% of your dwelling coverage, and inspection requirements for roofs 15 years or older. Getting any one of these wrong can cost you the entire claim.
Here is a quick reference for the key rules homeowners in Pompano Beach need to know:
|
Rule |
What It Means |
|
1-Year Filing Deadline |
Homeowners have 1 year from the date of damage to file a roof claim; supplemental claims must be filed within 18 months. |
|
Hurricane Deductible |
A separate deductible of 2 to 5 percent of insured structure value applies when a named hurricane triggers the claim. |
|
RCV vs. ACV |
Replacement Cost Value policies pay full repair cost minus the deductible, while Actual Cash Value policies subtract depreciation, producing a significantly lower payout on older roofs. |
|
15-Year Inspection Rule |
Many newer Florida policies require inspections for roofs 15 years or older and may pay only Actual Cash Value rather than Replacement Cost Value. |
According to the Florida Office of Insurance Regulation, recent reforms have changed how claims are handled, and stricter underwriting and rising premiums mean homeowners need to be more informed than ever before.
Documentation is everything; claims get denied not because damage did not exist, but because homeowners could not prove it. Working with a licensed Florida roofing contractor from day one significantly improves claim outcomes, since the adjuster works for the insurance company, not for you.
Steps to Take Immediately After Storm Damage
Taking the right actions in the right order protects both your property and your claim:
1. Stay safe first. Do not access a damaged roof without professional equipment or training.
2. Document everything. Photograph all visible damage from the ground before any cleanup or temporary repairs begin.
3. Apply temporary protection. Tarping or boarding open areas stops secondary water intrusion, which insurers may otherwise classify as a separate, uncovered loss.
4. Schedule a professional inspection. A licensed contractor produces a written damage report that supports your claim with specific measurements and material assessments.
5. File promptly. File your storm damage claim as soon as temporary protection is in place. Florida law generally requires hurricane-related roof claims to be filed within one year of the date of loss, and filing promptly strengthens the claim by giving the adjuster time to evaluate fresh damage rather than deteriorated conditions.
Choosing the Right Roofing Contractor in Pompano Beach
Broward County’s coastal environment demands specific expertise. Shingle roofs, tile roofs, and flat membrane systems each respond differently to wind and rain, and each requires a different repair approach. Before signing any contract, confirm the following:
• Active Florida state roofing license
• Proof of general liability and workers’ compensation insurance
• Familiarity with Broward County permitting requirements
• Experience with both residential and commercial roofing systems
• Willingness to provide a written inspection report before any work begins
Pro Contractors USA offers guidance, education, and support for maintaining roofs and other home systems, with a mission to provide best-in-class service for residential and commercial properties. The company positions itself around home improvement services designed to help homeowners weather any storm.
Frequently Asked Questions
Does homeowners insurance cover all storm roof damage in Florida? Not automatically. Standard homeowners insurance in Florida covers roof damage caused by covered perils, which typically include wind, hail, fire, falling objects, and the weight of ice or snow. Gradual wear and maintenance issues are excluded.
What is the 25% rule for Florida roofs? Florida’s 25% rule for roof damage allows leeway for insurance companies to accept liability for a repair instead of replacement of the damaged roof. If damage exceeds 25% of the roof area, a full replacement may be required under the Florida Building Code.
How long does a storm roof claim take in Florida? Timelines vary by insurer and damage scope, but understanding the timeframes for filing storm damage claims is non-negotiable, as Florida law mandates strict deadlines for initial claims, supplemental claims, and lawsuits related to hurricane insurance.
Should I get a contractor inspection before calling my insurer? Yes. A contractor inspection creates an independent damage record before the insurance adjuster visits, giving you a baseline to compare against the insurer’s estimate.
Storm damage recovery in Pompano Beach moves fast, and so do claim deadlines. Scheduling a professional roof inspection immediately after a weather event is the single most effective step a homeowner can take to protect both their property and their coverage. To get started with a local roofing assessment, contact Pro Contractors USA and request a free inspection before the filing window closes.


